For both sides
Cannabis excise and potency taxes by state
Federal and state law current as of September 2026 — verify with counsel.
State cannabis excise taxes in 2026 range from Missouri's 6% retail tax to Washington's 37%. Most states tax the retail price; Colorado, Nevada, New York, Illinois and, since 1 January 2026, Michigan also tax the wholesale transfer. Illinois taxes by THC potency band, and Connecticut taxes per milligram of THC until a flat 10.75% rate replaces it on 1 October 2026.
Key takeaways
- California's cannabis excise tax went from 15% to 19% on 1 July 2025 and back to 15% on 1 October 2025 under AB 564, which holds it there until 30 June 2028.
- Michigan added a 24% wholesale excise tax on adult-use marihuana on 1 January 2026, on top of the 10% retail excise and 6% sales tax.
- Maryland raised its cannabis sales tax from 9% to 12% and Minnesota raised its gross receipts tax from 10% to 15%, both on 1 July 2025.
- New Mexico's cannabis excise rate is 14% from 1 July 2026 to 30 June 2027 and is scheduled to keep rising annually.
- Collected excise tax is money held for the state; unremitted balances follow the business in an equity sale and can follow the assets under state successor-liability rules.
How do states tax cannabis?
States use four designs, often stacked:
- Retail excise, as a percentage of price. The most common. Collected by the retailer from the customer.
- Wholesale or cultivation tax. A percentage of the first sale or transfer from a grower or processor, or a fixed amount per ounce or pound.
- Potency tax. A rate that varies with THC content or a fixed amount per milligram of THC.
- General sales tax and local cannabis taxes on top of the above.
These are separate from income tax. Federal section 280E and state 280E decoupling concern income tax; excise taxes are owed whether or not the business makes a profit.
State cannabis excise rates in 2026
Rates are state-level adult-use rates as of September 2026 unless noted. General sales tax and local cannabis taxes are extra. Rates change often; confirm with the linked revenue department before relying on any figure.
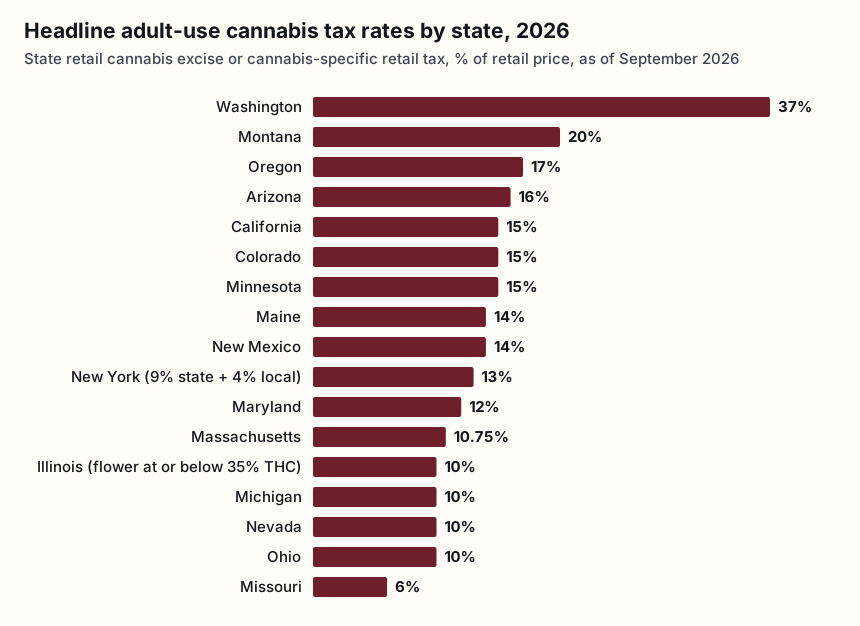
| State | Retail excise | Wholesale, cultivation or potency tax | Source and notes |
|---|---|---|---|
| California | 15% of gross receipts | None since the cultivation tax ended | CDTFA: 19% from 1 Jul 2025, back to 15% on 1 Oct 2025 under AB 564, held until 30 Jun 2028 |
| Washington | 37% | None | RCW 69.50.535 |
| Colorado | 15% retail marijuana sales tax | 15% excise on first transfer, on average market rate or contract price | Colorado DOR |
| Michigan | 10% | 24% wholesale excise from 1 Jan 2026 | Michigan Treasury; 6% sales tax also applies |
| Illinois | 10% at or below 35% THC; 25% above 35% THC; 20% infused products | 7% cultivation privilege tax on first sale | Illinois DOR |
| New York | 13% (9% state, 4% local) | 9% on distributor sales to retailers, which replaced the per-milligram THC tax on 1 Jun 2024 | Tax Foundation, Jan 2026 |
| New Jersey | No state excise percentage; sales tax applies | Social Equity Excise Fee of $2.50 per ounce sold by cultivators, held flat for 2026 | NJ Division of Taxation |
| Connecticut | Flat 10.75% from 1 Oct 2026 | Until then, per milligram of total THC: $0.00625 plant material, $0.0275 edibles, $0.009 other | Connecticut DRS |
| Maryland | 12% from 1 Jul 2025, up from 9% | None | Comptroller of Maryland |
| Minnesota | 15% gross receipts tax from 1 Jul 2025, up from 10% | None | Minnesota DOR |
| New Mexico | 14% from 1 Jul 2026 to 30 Jun 2027 | None | NM Taxation and Revenue; scheduled annual increases |
| Massachusetts | 10.75% | None | Tax Foundation, Jan 2026; 6.25% sales tax and up to 3% local option also apply |
| Oregon | 17% | None | Tax Foundation, Jan 2026; localities may add up to 3% |
| Nevada | 10% | 15% of fair market value at wholesale | Tax Foundation, Jan 2026 |
| Arizona | 16% | None | Tax Foundation, Jan 2026 |
| Montana | 20% | None | Tax Foundation, Jan 2026 |
| Ohio | 10% | None | Tax Foundation, Jan 2026 |
| Missouri | 6% | None | Tax Foundation, Jan 2026; local taxes may apply |
The Tax Foundation also reports that Maine lowered its per-pound cultivation taxes and raised its retail rate from 10% to 14% for 2026, and that Alaska taxes by weight at the cultivation level rather than by price.
Why potency and wholesale taxes matter more than the headline rate
Wholesale taxes hit producers directly. A retail excise is collected from the customer. A wholesale tax is a cost to the grower or processor, who may or may not be able to pass it on. Michigan’s 24% tax arrived in a market already known for falling wholesale prices, so a cultivation business there should be valued on results since 1 January 2026, not on 2025 margins. See selling in an oversupplied market.
Vertically integrated operators are taxed on a deemed price. Where there is no arm’s-length sale, the state supplies one. Colorado applies its 15% excise to an average market rate that the Department of Revenue publishes. If that rate sits above what the product would actually fetch, an integrated operator pays more tax per pound than an independent grower selling at the real price.
Potency bands shape product mix. In Illinois the step from 10% to 25% at 35% THC makes concentrates and vapes carry a much heavier tax than flower. A store’s blended excise rate, and its gross margin after tax, depend on what it sells. Connecticut’s shift to a flat rate on 1 October 2026 will change relative shelf prices there, so trailing sales mix may not predict the next twelve months.
What excise taxes mean in a sale
- Collected tax is not the seller’s money. Excise and sales tax collected from customers are held for the state. Buyers should reconcile tax returns to point-of-sale and track-and-trace sales, month by month.
- Arrears follow the deal. In an equity sale the liability stays inside the company. In an asset sale, state successor-liability rules can make the buyer answerable unless a tax clearance is obtained. The mechanics are in tax liabilities and holdbacks in a sale and selling with tax delinquency.
- Use the current rate in the numbers. A business that earned its trailing profit under a lower rate is worth less under the higher one unless prices moved. Illustrative: a retailer with $4,000,000 of sales that absorbs a 3-point increase loses about $120,000 of annual pre-tax profit; at a 4 times multiple that is $480,000 of value.
- Excise tax is not deductible relief from 280E. How an excise tax is treated on the federal return, as part of cost of goods sold, as a reduction of receipts, or as a disallowed expense, depends on who the tax is legally imposed on. Ask the target’s CPA how each tax was handled.
- Local taxes can exceed the state’s. City and county cannabis business taxes vary widely; check the relevant city page and the local approvals page.
This page is general education, not tax advice. Rates were checked in September 2026 and legislatures change them frequently.
Frequently asked questions
Which state has the highest cannabis excise tax?
Washington has the highest single state rate, a 37 percent excise on the retail selling price under RCW 69.50.535, with general sales tax on top. Stacked systems can approach or exceed it: Michigan now combines a 24 percent wholesale tax, a 10 percent retail excise and 6 percent sales tax, and Illinois charges up to 25 percent at retail plus a 7 percent cultivation tax and state and local sales taxes.
What is a cannabis potency tax?
A potency tax is set by THC content rather than price alone. Illinois applies a 10 percent purchaser excise to cannabis at or below 35 percent THC, 25 percent above 35 percent THC, and 20 percent to infused products. Connecticut has charged a fixed amount per milligram of total THC that varies by product type, and is replacing it with a flat percentage on 1 October 2026.
Are medical cannabis sales subject to state excise tax?
Often not, or at a lower rate. Illinois exempts medical purchases from the purchaser excise tax and applies a 1 percent sales tax. Washington exempts qualifying medical sales at endorsed stores. Michigan's retail excise and new wholesale tax apply to adult-use marihuana. The details are state specific, so a dual-license store's blended tax rate depends on its medical share.
Who is legally responsible for paying cannabis excise tax, the customer or the business?
It depends on the tax. Retail excise taxes are usually imposed on the purchaser and collected by the retailer, which makes the retailer liable for remitting what it collected. Wholesale taxes such as Michigan's 24 percent tax and Illinois's 7 percent cultivation privilege tax are imposed on the cultivator or processor making the first sale, so they are a direct cost of the producer.
How do excise tax changes affect what a cannabis business is worth?
A rate increase that cannot be passed on in price comes straight out of margin. A retailer that absorbs a three point increase on 4,000,000 dollars of sales loses about 120,000 dollars of annual pre-tax profit. Buyers therefore look at trailing results under the current rate, not the old one, and ask whether any scheduled increase is already reflected in the forecast.
Sources
- California Department of Tax and Fee Administration — Cannabis retailers, excise tax rate and AB 564 — https://cdtfa.ca.gov/industry/cannabis/retailers.htm
- Michigan Department of Treasury — Treasury releases guidance on new 24% wholesale marijuana tax (17 March 2026) — https://www.michigan.gov/treasury/news/2026/03/17/michigan-treasury-releases-guidance
- Comptroller of Maryland — Sales and use tax alert (22 May 2025) — https://www.marylandcomptroller.gov/legal-library/sut-ta-may-22-2025.html
- Minnesota Department of Revenue — Cannabis tax — https://www.revenue.state.mn.us/cannabis-tax
- New Mexico Taxation and Revenue Department — Cannabis excise tax — https://www.tax.newmexico.gov/businesses/cannabis-excise-tax/
- New Jersey Division of Taxation — Social Equity Excise Fee (SEEF) — https://www.nj.gov/treasury/taxation/cannabis/recreational/seef.shtml
- Illinois Department of Revenue — Cannabis taxes — https://tax.illinois.gov/research/taxinformation/other/cannabis-taxes.html
- Connecticut Department of Revenue Services — Cannabis tax information — https://portal.ct.gov/drs/taxes/cannabis/cannabis-tax
- Washington State Legislature — RCW 69.50.535, cannabis excise tax — https://app.leg.wa.gov/rcw/default.aspx?cite=69.50.535
- Colorado Department of Revenue — Marijuana excise tax — https://tax.colorado.gov/marijuana-excise-tax
- Tax Foundation — 2026 recreational marijuana taxes by state (January 2026) — https://taxfoundation.org/data/all/state/recreational-marijuana-taxes/